Fee-Only vs Commission vs Percentage - How Financial Advisors Charge
Understand how financial advisors charge in Australia. Compare fee-only, percentage-based, and commission structures, including ASIC rules and realistic costs.
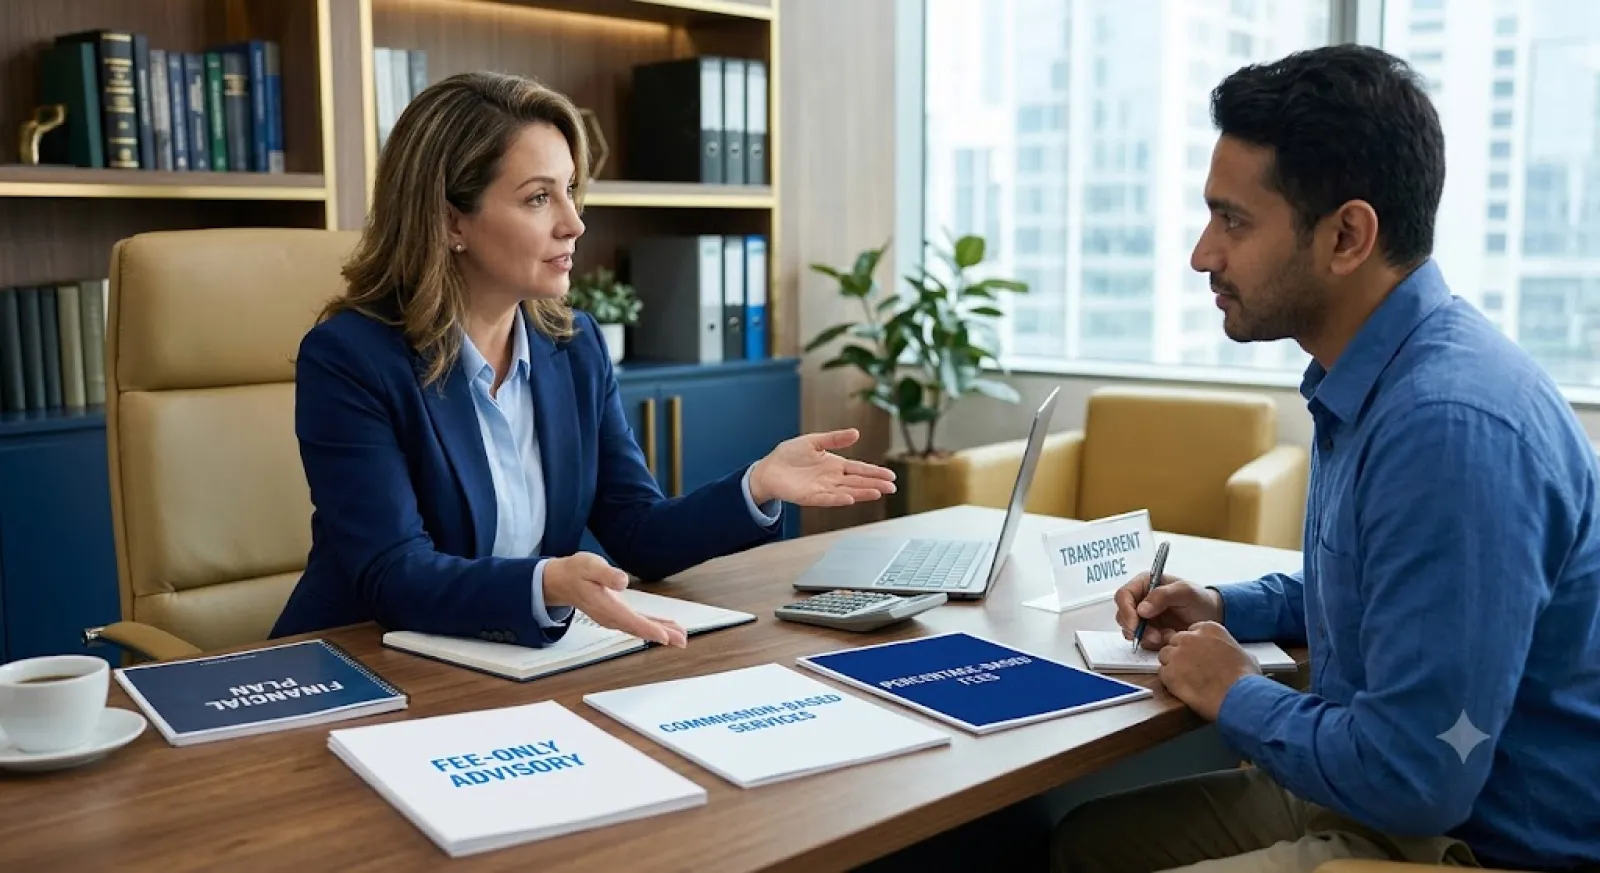
Seeking professional wealth management advice in Australia—whether to structure superannuation, plan for retirement in suburban Melbourne, manage an investment portfolio in Sydney, or protect a family business in regional Queensland—involves an essential first step: understanding how you will be charged.
The financial advisory industry in Australia has undergone sweeping regulatory changes over the past decade. Reforms stemming from the Future of Financial Advice (FOFA) legislation and the Banking Royal Commission have fundamentally reshaped advisor remuneration, largely eliminating hidden kickbacks and conflicts of interest. However, navigating the distinction between fee-only, percentage-based (assets under management), and commission-based models remains a crucial task for consumers.
This guide provides a detailed analysis of how a Financial Advisor in Australia charges for their services, the laws that govern advisory pricing, typical fee ranges, and how to select the right fee structure for your personal financial goals.
The Three Primary Advisory Fee Models Explained
Financial advisers in Australia generally charge clients using one of three fee models—or a hybrid combination, depending on the scope of advice and products recommended.
1. Fee-Only (Fixed Dollar or Hourly Rate)
Under a fee-only structure, a Financial Planner in Australia charges a transparent flat dollar amount or hourly rate for their expertise, regardless of the size of your investment portfolio or the financial products selected.
-
How it Works: You pay directly for the time, strategy development, and documentation (such as a Statement of Advice).
-
Typical Structure:
-
Statement of Advice (SoA): $3,000 to $6,600+ flat fee.
-
Hourly Rates: $300 to $600 per hour depending on seniority and location.
-
Ongoing Flat Retainer: $3,500 to $5,000+ per year.
-
-
Best For: Investors who want unbiased strategic planning, advice on structural issues (like debt reduction or Self-Managed Super Fund setup), or individuals who prefer absolute cost certainty.
2. Percentage-Based Fee (Assets Under Management - AUM)
In an AUM arrangement, the fee is calculated as a fixed percentage of the total assets the advisor manages on your behalf.
-
How it Works: If an advisor manages $800,000 of your superannuation and investments at an agreed annual fee of 1.0%, you pay $8,000 per year.
-
Tiered Fee Scale: Most planners reduce the percentage tier as portfolio size increases (e.g., 1.0% on the first $500,000; 0.6% on amounts between $500,000 and $1,500,000; 0.3% thereafter).
-
Typical Range: 0.50% to 1.50% per annum.
-
Best For: High-net-worth investors or retirees seeking ongoing active portfolio management and rebalancing.
Important Regulatory Note: Under Section 923A of the Corporations Act 2001, an advisor cannot legally call themselves an Independent Financial Adviser in Australia if they charge asset-based fees (percentage of portfolio). To hold true "independent" status, the firm must charge pure flat-dollar fees and accept zero product commissions or volume incentives.
3. Commission-Based Remuneration (Restricted Scope)
Historically, financial planners earned substantial commissions from product manufacturers, insurance companies, and managed funds. Following federal legislative reforms, conflicted remuneration and product commissions on investment products, superannuation, and pension accounts are strictly illegal in Australia.
-
The Exception – Personal Risk Insurance: Financial advisors are still legally permitted to receive commissions from insurance companies when arranging personal risk insurance policies (Life Insurance, Total and Permanent Disability / TPD, Trauma, and Income Protection).
-
Regulatory Caps: Under the ASIC Corporations (Life Insurance Commissions) Instrument, insurance commissions are strictly capped:
-
Upfront Commission: Maximum 60% of the first-year policy premium (plus GST).
-
Ongoing (Trail) Commission: Maximum 20% of the annual premium for each year the policy remains active.
-
-
Rebate Option: Many fee-only advisors rebate 100% of these insurance commissions back to the client in exchange for charging an upfront fee, which lowers the client’s ongoing insurance premium.
Comparison Matrix: Fee Models Side-by-Side
| Feature / Model | Fee-Only (Flat Dollar) | Percentage-Based (AUM) | Commission (Risk Insurance Only) |
| Payment Source | Direct from client (out-of-pocket or super) | Deducted directly from investment balance | Paid by the insurance provider |
| Transparency | High (exact dollar value disclosed upfront) | Moderate (dollar fee increases as assets grow) | Moderate (must be fully disclosed in SoA) |
| Conflict Potential | Minimal (advisor paid for strategy, not products) | Moderate (advisor motivated to keep assets under management) | High (incentive to recommend higher-premium policies) |
| Upfront Cost Range | $3,000 – $6,600+ | $0 – $3,000 initial setup fee | $0 out-of-pocket (covered by policy commission) |
| Ongoing Cost Range | $3,500 – $6,000 p.a. fixed | 0.5% – 1.5% of total portfolio value p.a. | Included in monthly insurance premium |
Australian Rules, Regulations, and Consumer Guarantees
Financial advice in Australia is governed by strict federal legislation designed to protect consumers from misconduct, unquantified fees, and poor advice.
Key Consumer Protection Regulations
-
Best Interests Duty: Section 961B of the Corporations Act 2001 requires any Financial Advisor in Australia to place their client's interests above their own when delivering personal advice.
-
Annual Fee Renewal (Opt-In Reforms): Ongoing advice contracts must be renewed annually. Advisors cannot automatically deduct ongoing fees from a bank account or superannuation fund without obtaining written client consent every 12 months.
-
Statement of Advice (SoA): Before any recommendations are executed, your advisor must provide a formal SoA clearly stating the total dollar fees you will pay for both initial and ongoing advice.
-
Professional Standards & Qualifications: Financial planners must hold an approved degree, pass the national financial adviser examination, complete annual Continuing Professional Development (CPD), and be registered on the ASIC Financial Advisers Register (FAR).
Typical Costs of Financial Advice in Australia
The median cost of ongoing personal financial advice in Australia sits at approximately $4,837 per year, according to current industry benchmarks. However, actual expenses vary based on the scope and complexity of your requirements.
What Factors Influence the Price?
-
Scope of Advice: Single-issue advice (such as assessing superannuation options) costs significantly less than a comprehensive strategy covering tax minimisation, retirement projection, wealth protection, and estate planning.
-
Entity Structures: Incorporating Self-Managed Super Funds (SMSFs), discretionary family trusts, or private corporate structures adds compliance overhead.
-
Geographic Market Differences: Practices located in central business districts like Sydney or Melbourne often maintain higher overheads than firms based in regional cities like Newcastle, Geelong, or Toowoomba, which can influence pricing models.
-
Payment via Superannuation: Under Australian tax and superannuation guidelines, certain fees for advice directly related to your superannuation assets (e.g., investment allocation within super) can be deducted directly from your super balance rather than paid out-of-pocket.
Practical Examples: Evaluating Advice Models in Real Life
Case Study A: First-Home Buyer & Super Accumulator in Sydney
-
Client Scenario: A couple in their early 30s seeking advice on debt management, budget structuring, and optimizing their superannuation portfolios.
-
Best Model: Fee-Only (Fixed Dollar Fee).
-
Cost Outcome: They pay an upfront flat fee of $3,500 for a Statement of Advice. Because they do not need ongoing asset management, they avoid paying 1.0% p.a. on their super balance, saving thousands in compound fees over time.
Case Study B: Pre-Retirees in Suburban Adelaide
-
Client Scenario: A couple aged 62 with $1.4 million across superannuation and personal investments preparing to transition into retirement.
-
Best Model: Percentage-Based (AUM) or Fixed Annual Retainer.
-
Cost Outcome: Under a 0.75% AUM structure, they pay $10,500 annually for continuous portfolio monitoring, pension drawdowns, aged care planning, and annual tax review strategies. Alternatively, under a flat-fee model, they might pay $6,000 annually.
Consumer Checklist: Questions to Ask Before Hiring an Advisor
Use this practical checklist during your initial discovery consultation to ensure full fee transparency:
-
[ ] Are you an Authorised Representative? Check their name on the official ASIC Financial Advisers Register (FAR) to confirm their credentials and licensing status.
-
[ ] Can you call yourself an "Independent Financial Adviser"? If they claim independence under s923A of the Corporations Act, confirm they receive zero product commissions and do not charge asset-based fees.
-
[ ] How exactly will I be billed? Request a full itemised breakdown in dollar terms (e.g., $4,000 upfront) rather than just a percentage figure.
-
[ ] Do you accept insurance commissions? If yes, ask whether they are willing to rebate commissions in exchange for an upfront fee.
-
[ ] What is included in the ongoing service? Ask how many face-to-face or virtual meetings are provided each year and what reports you will receive.
-
[ ] Can fees be paid from my superannuation? Clarify what portion of the Statement of Advice fee can legally be debited from your super fund balance.
Find Local Accounting & Financial Services and Australian Information on AusLocaly
Choosing the right financial advice professional is one of the most important decisions you can make for your long-term wealth. AusLocaly provides a structured directory to help Australian residents, families, and business owners discover professional services in their local area.
Whether you are looking for qualified advisors and accountants in major capital cities like Sydney, Melbourne, or Brisbane, or seeking financial professionals across regional Australia, explore our comprehensive categories page to research trusted local providers near you.
Related Topics & Tags
Sophie explores the relationship between local businesses and the people living around them. Her work covers neighbourhood retailers, hospitality venues and service providers. She is interested in the everyday reasons people choose local businesses. Her writing brings a community perspective to business discovery.